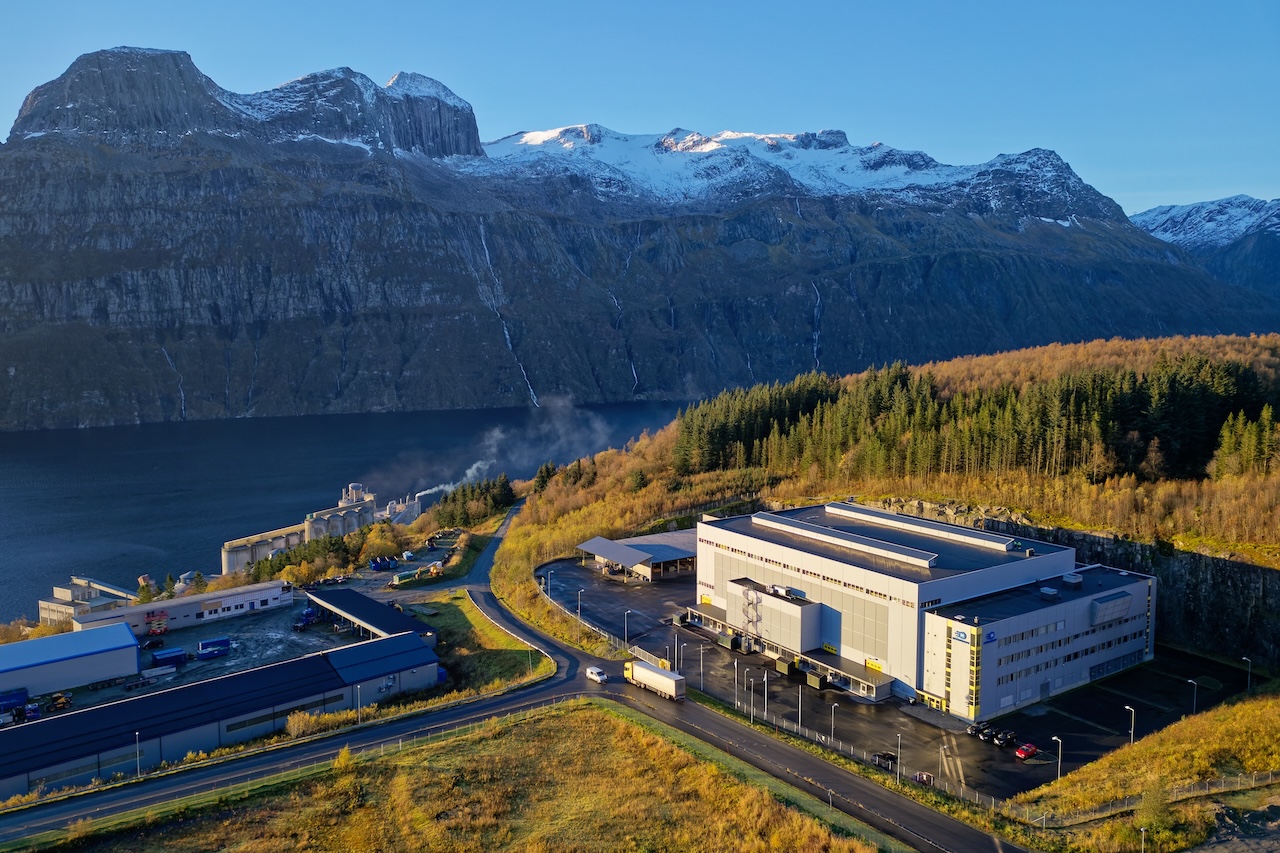
Nscale, the London-based AI cloud provider backed by Nvidia, has filed for a New York Stock Exchange IPO targeting a valuation of up to $35 billion. The S-1, dated September 18, 2026 (UTC-4), reveals a company with explosive revenue growth, $103.4 billion in contracted future revenue — and a going-concern warning from its auditors.
The numbers behind the filing
Nscale's first-half 2026 results tell a story of hypergrowth paired with heavy losses. Revenue hit $141 million, up 1,252% year-over-year, while net losses reached $1 billion — though most of that loss came from non-cash charges. The company employs about 450 people at its UK headquarters and operates data centers in Norway, Portugal, and the UK, with a planned campus in Iceland.
The contract backlog is what makes the IPO story compelling. Nscale disclosed $103.4 billion in remaining performance obligations over the next seven years. Anthropic alone committed $44.6 billion for compute at Nscale's West Virginia data center campus. Microsoft is another major customer, and Nscale partnered with OpenAI on the Stargate Norway project.
| Metric | Value | Source |
|---|---|---|
| Target valuation | Up to $35B | Financial Times |
| H1 2026 revenue | $141M | S-1 filing |
| H1 2026 net loss | $1B | S-1 filing |
| Revenue growth (YoY) | 1,252% | S-1 filing |
| Contracted revenue (7yr) | $103.4B | S-1 filing |
| Anthropic commitment | $44.6B | S-1 filing |
| Nvidia stake | 5%+ | S-1 filing |
| Nvidia convertible note | $3.1B (Sept 15) | Fortune |
| March 2026 Series C | $2B | PR Newswire |
The Nvidia connection — and the red flag
Nvidia's role in Nscale goes beyond being a chip supplier. The company holds a stake of over 5% and, on September 15, 2026 (UTC-4), injected $3.1 billion in exchange for unsecured convertible loan notes. That cash infusion came just days before the S-1 became public — and it's part of why the auditors flagged going-concern risk.
The filing reveals that Nscale's auditors expressed substantial doubt about the company's ability to continue as a going concern. In plain English: the company is burning cash so fast that, without continued access to capital markets or strategic investors like Nvidia, it might not survive. The $3.1 billion from Nvidia bought time, but the IPO itself is arguably a necessity rather than a choice.
Why it matters
Nscale's IPO is the first major AI infrastructure listing since the industry's safety debate intensified in September 2026, and it maps out the economics of the "neocloud" sector with unusual clarity. The $103.4 billion contract backlog sounds enormous — until you compare it to the capital required to fulfill it. Nscale is essentially a bet that AI model training demand will keep growing fast enough to justify building data centers years in advance.
The revenue multiple tells the real story. At a $35 billion valuation and $141 million in H1 revenue (roughly $282 million annualized), Nscale is trading at about 124x annual revenue. That's extreme even by AI infrastructure standards. CoreWeave, the closest comparable, went public in 2025 at roughly 30x revenue. The premium reflects Nscale's contract backlog and Nvidia's endorsement, but it also prices in a future that hasn't happened yet.
The Anthropic concentration is worth watching closely. One customer accounts for 43% of the entire contract backlog. If Anthropic's compute needs shift — say, if it moves workloads to its own data centers or to a competitor like Oracle or AWS — Nscale's revenue visibility deteriorates dramatically. The same risk applies to the broader thesis: these are seven-year contracts in an industry where model architectures and hardware roadmaps change every 12-18 months.
The critical lens
There's a circularity to Nscale's financing that deserves scrutiny. Nvidia invests in Nscale, Nscale buys Nvidia GPUs, Nscale signs contracts with AI labs that are themselves funded by Nvidia-adjacent capital, and then Nscale goes public at a valuation that rewards the whole chain. This isn't unique to Nscale — the entire AI infrastructure sector runs on this kind of circular financing — but the going-concern warning makes it more visible here than elsewhere.
The 1,252% revenue growth is impressive, but it's off a tiny base. $141 million in H1 revenue against $1 billion in losses means the company is losing roughly $7 for every $1 of revenue. Even granting that most losses are non-cash, the cash burn is real and ongoing. The $3.1 billion Nvidia note, the $2 billion Series C from March, and now the IPO — Nscale has raised over $5 billion in 2026 alone and still needs public markets. That tells you something about the capital intensity of this business.
What to watch next
The IPO pricing will be the first real test. If Nscale prices at $35 billion, it validates the neocloud model and likely opens the door for CoreWeave competitors and European infrastructure players to follow. If it prices closer to $20-25 billion, it signals that investors are starting to question the circular financing structure.
Watch Anthropic's behavior post-IPO. If Anthropic renegotiates or scales back its $44.6 billion commitment, that's the canary in the coal mine for the entire contract-backlog model. Also watch whether Nvidia converts its $3.1 billion note into equity at the IPO price — that would be a strong vote of confidence, while holding it as debt would be more cautious.
The going-concern warning won't disappear after the IPO. Nscale will need to show, over the next 2-3 quarters, that it can convert contracted revenue into actual cash flow without returning to capital markets every six months. If it can't, the $35 billion valuation will look like a peak, not a foundation.
No comments yet